Showing posts with label AMGN. Show all posts

Saturday, July 25, 2009

Decoupled moves in Biotech indices highlight opportunities and challenges

The chart below shows returns for the last 6 months of the two Biotech indices that I follow: BTK and NBI.

After a significant and equivalent downside move in March, both indices have turned positive with an explosive move since middle of July. I speculate that the March downside move was a response to concerns over Obama's health care proposal and its impact on Medicare. However, upon further examination, the adjustments in Medicare rebates would translate to no more than a double digit change in revenues. Moreover, the biotech story is in large a product story where launch of a new product has a much higher impact on revenues than any adjustments in rebate system which can be overcome with cost and price adjustments and while keeping healthy profit margins.

The explosive returns in July are rather interesting and may be indicative of things to come. The divergence in the charts of two indices (35% return for BTK vs. 12% for NBI) underlying story of the biotech industry. This trend indicates a value disparity between mid-large cap biotechs and smaller companies. The BTK move can be contributed to recent earnings and product advancement reports coming out of Celgene (CELG), Gilead (GILD), Amgen (AMGN) and other pharma companies that highlight decent earnings growth despite a challenging environment in addition to value added product development successes.

The M&A activity over the last few quarters have just contributed positively to perceived value of these stocks as the recent acquisition of Medarex (MDRX) highlights a larger trend of big pharma acquiring biologics assets and capabilities. This has resulted in speculative run-ups in shares of other companies such as Elan(ELN) and Seattle Genetics (SGEN) who have biologic portfolios. This trend, however, could reverse as rapidly if no new deals are announced in the next few months.

The muted returns in the NBI index highlights the financing concerns that still remain for smaller companies which may cause a wave of consolidations, bankruptcies and asset sales at depressed values.

My favorite large cap names are Genzyme (GENZ) and Amgen(AMGN) and Biomarin (BMRN) and Vertex (VRTX) among mid-sized companies.

Disclosure: The author has no direct stock or option positions in any of the stocks mentioned in this article.

Saturday, December 02, 2006

Amgen (AMGN)- Large cap biotechnology stock with growth ahead

One of the major attractions of investors to Biotechnology stocks is the promise of exponential growth. There are not many industries where a stock can go with no revenues for up to ten years and with a sudden FDA approval decision have the potential to have hundreds of million to billions in revenues.

One quick look at the large cap Biotechnology stocks reveals the past winners of this strategy including Genentech (DNA), Biogen-Idec (BIIB), Genzyme (GENZ) and the subject of this article, Amgen (AMGN). These companies have all had tremendous success by getting drugs into the market and have reaped the rewards in form of their stocks growing into billions of dollars in market capitalization. One of the downside of this large growth is that the growth rate diminishes over the years. The days of 100-200% earnings growth rates for these large cap biotech stocks has been replaced with 10-20% returns.

However, having consistent revenues and earnings in addition to product sales data allows investors to quantify the valuation of the company and assess whether a price is fairly valued.

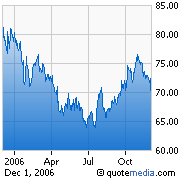
Amgen is currently trading at $69.38 ( as of 12/1/2006) with a market cap of $81 billion and earnings of $3.93 per share in 2006 and expected $4.41 per share in 2007. This translates to an earnings growth rate of 12% and a PE ratio of only 15.7 going into 2007. PEG (PE to growth ratio) is at 1.3 which puts it in the inexpensive category. The PE in particular is very low compared to historical ratios for Amgen and for the industry and I anticipate the fair value PE to be around 25. Taking into account a 20% discount for unforeseen risks, I come up with a price target of $88.

Amgen has launched many new products in the last few years including the latest, Vectibix to treat colon cancer (will compete with Erbitux from Imclone at 20% priced discount) and more product progression updates to come in 2007.

Some of the risk to Amgen include competition to its best selling drug Epogen and a law suite from J&J. I will not go into details with the law suite but Amgen has a very good chance of winning this case which would remove some risks and push the stock higher.

Bottom line: Amgen is a best of breed large cap biotechnology stock which can add significant stability and decent growth to any portfolio. When it's price drops due to market conditions and when this drop is clearly not based on company's fundamentals it should be considered under valued.

I recommend buying at $69 ( and more aggressively at lower prices) with a 12 month target of $88.

JMHO